For many families, planning a move to assisted living raises an immediate financial question: Does the house have to be sold? Not necessarily.
Paying for assisted living without selling the house may be possible by combining existing income, benefits, insurance and home equity strategies. Understanding the options can help families make a plan that supports a loved one’s needs without rushing into a home sale.
Keeping the house may also provide flexibility. A family might rent the property, preserve it for future use or simply wait before making a long-term decision. Here are several ways families may be able to afford senior living and keep the home.
Use Rental Income to Help Cover Senior Living Costs
Renting the house can create monthly income that helps offset assisted living expenses. This approach may be worth considering when the property is in good condition, there is rental demand in the area and the family is comfortable remaining responsible for the home.
A property management company can handle tenant screening, rent collection and maintenance for a fee. This may make keeping the house while paying for care more manageable, especially when family members do not live nearby.
Before renting, families should consider expenses such as property taxes, insurance, repairs, management fees and periods when the house could be vacant. Looking at expected net rental income rather than rent alone provides a more realistic picture of how much the property can contribute each month.
Explore Whether a Reverse Mortgage Is an Option
A reverse mortgage may allow eligible homeowners age 62 or older to access part of their home equity without immediately selling the property. Depending on the loan, funds may be available through a lump sum, monthly payments or a line of credit.
Important considerations can include:
- Eligibility and occupancy requirements
- Interest, fees and other loan costs
- When the loan becomes due
- How the arrangement could affect heirs and the home
Reverse mortgages have specific requirements, so they will not work for every family or every senior living move. Anyone considering this type of assisted living payment without a house sale should review the terms carefully with qualified financial and lending professionals.
Review Long-Term Care Insurance Benefits
Long-term care insurance may be another resource for financing assisted living options without a home sale. Depending on the individual policy and eligibility requirements, benefits may help with qualifying senior living expenses.
Families reviewing an existing policy should look closely at:
- Daily or monthly benefit limits
- Waiting or elimination periods
- Covered services and eligibility requirements
- The policy’s maximum benefit period or amount
Contacting the insurance provider before a move can clarify what documentation is needed and whether expenses associated with assisted living qualify under the policy.
At The Gardens of Bellaire, Assisted Living provides support with everyday needs alongside services such as weekly housekeeping, scheduled transportation and freshly prepared homestyle dining. These inclusive services are worth considering when comparing senior living expenses with the combined costs of maintaining a house and arranging support separately.
Ask About Veterans Benefits
Some veterans and surviving spouses may qualify for Department of Veterans Affairs benefits that can help with eligible long-term support expenses. Eligibility and benefit amounts depend on several factors, so families should confirm current requirements directly with the VA or an accredited veterans benefits professional.
Gathering military service, financial and other required documentation early may make the application process easier. For eligible families, veterans benefits can become one part of a broader plan for paying senior living expenses while preserving other assets.
Consider Home Equity Financing Carefully
A home equity line of credit, or HELOC, is another potential alternative to selling a home for care. A HELOC allows qualified homeowners to borrow against available equity, typically up to an approved credit limit.
Unlike a reverse mortgage, a HELOC generally requires repayment while the borrower is using the credit line. Interest rates may also change over time. Families should consider whether their ongoing income can comfortably support the required payments before using home equity for senior living expenses.
This option may be more appropriate as one piece of a larger financial plan rather than the sole source of ongoing funding.
Combine Financial Resources for Greater Flexibility
There's no single strategy that works for every family. In many cases, keeping the house while paying for care means combining resources instead of relying on one source.
Possible combinations include:
- Rental income plus retirement income or savings
- Long-term care insurance plus personal income
- Eligible veterans benefits combined with other resources
- Home equity financing paired with a sustainable repayment plan
A financial professional who understands senior living expenses, taxes, insurance and estate planning can help families compare alternatives to selling a home for care and understand the long-term effects of each choice.
Plan for the Full Cost of Assisted Living
Preserving a home can be meaningful, but the financial plan also needs to support a loved one’s day-to-day needs. When comparing options, look beyond the monthly housing payment and consider which services are included.
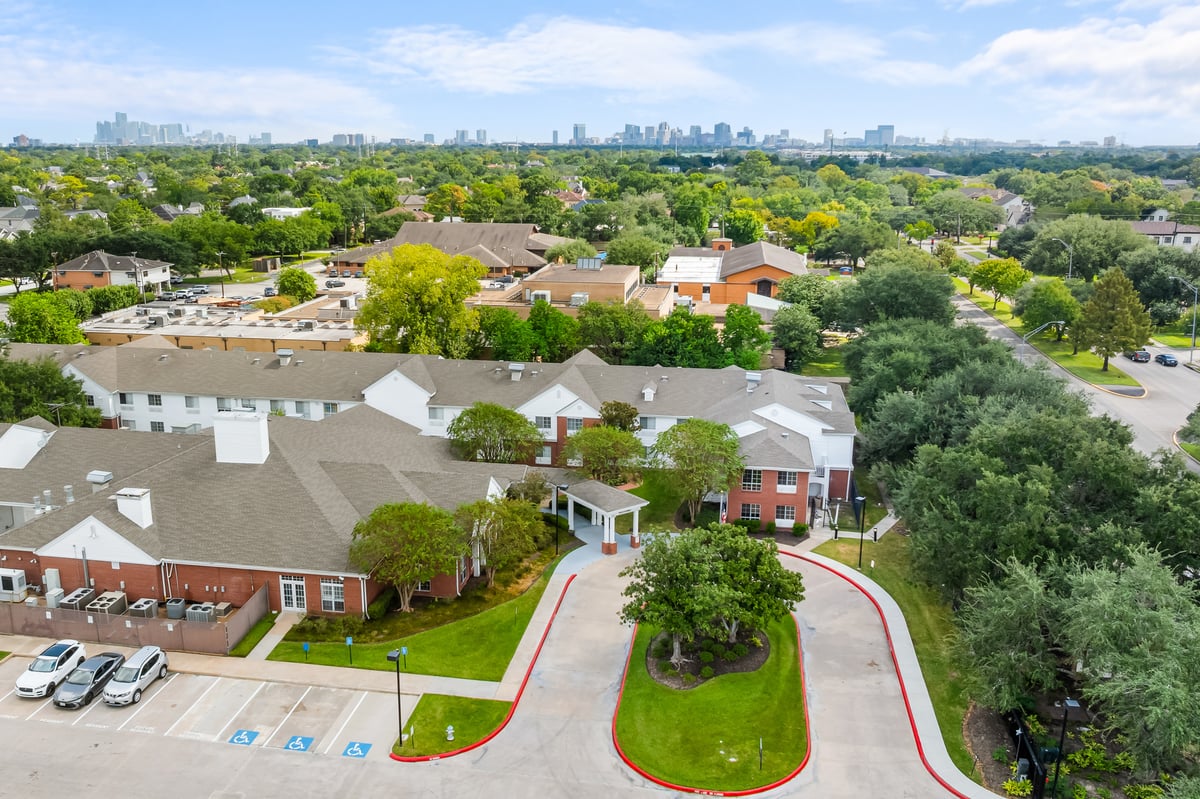
The Gardens of Bellaire offers Assisted Living in Bellaire, Texas, with apartment homes and services designed to simplify daily routines, including homestyle dining, housekeeping, scheduled transportation and a calendar of social and enrichment programs. Looking at what is included can give families a clearer comparison between remaining at home with separately arranged services and moving to a senior living community.
Paying for assisted living without selling the house can be possible, but the right approach depends on the homeowner’s finances, eligibility, property and long-term goals. Taking time to compare options can help families make a thoughtful decision without assuming a home sale is the only path forward.
Schedule a tour of The Gardens of Bellaire to explore Assisted Living, learn what is included and discuss the next steps for your family.